The challenge with charity clients is not that the filing deadlines themselves are especially complicated. It is that “charity” is not a single type of organisation.
In the UK, a practice may act for:
There are also Community Interest Companies (CICs) which are not charities but are often grouped in the same social-purpose category.
Those distinctions matter. The legal structure of the organisation, its jurisdiction and whether it also has Companies House obligations can affect what needs to be tracked.
It would be simple for practice management software to provide a single organisation type called “Charity”, but that loses information which can be useful to the practice.
A Charitable Company has a full Companies House registration as well as charity reporting requirements. CIOs and SCIOs are separate legal entities with basic Companies House listings. Charitable Associations and Charitable Trusts are unincorporated and do not have Companies House registrations.
CICs are different again. They are companies rather than charities and retain normal Companies House filing obligations.
That is why a single charity label only gets you so far. The underlying structure tells you something important about the client and the obligations that apply.
Accurate classification is essential before any automation takes place.
If the charity type is not properly recorded in a practice management system, firms have to rely on notes or create custom fields to identify what a client actually is. That can work, but it means creating and maintaining your own classification rather than having the organisation type recorded as part of the standard client information.
A firm should be able to quickly identify its Charitable Companies, Charitable Incorporated Organisations, Scottish Charitable Incorporated Organisations, Charitable Associations or Charitable Trusts, and view or filter them across the client base.
That makes it easier to review particular client groups, plan work and identify clients affected by a regulatory change. Properly structured information can also be used to determine the appropriate compliance work.
Organisation type is only part of the picture. Jurisdiction matters as well.
Charities in England and Wales are regulated by the Charity Commission for England and Wales, charities in Scotland by the Office of the Scottish Charity Regulator (OSCR), and charities in Northern Ireland by the Charity Commission for Northern Ireland.
The annual filing timetable illustrates the difference. Charities in England and Wales and Northern Ireland generally have ten months from their financial year end to make their annual submission, while Scottish charities have nine months.
Calculating nine or ten months from a year end is straightforward. The more important issue across a client base is making sure the right rule is applied to the right organisation.
For CIOs and SCIOs, the organisation type itself identifies the relevant jurisdiction. A Charitable Association or Charitable Trust, however, could be registered in England and Wales, Scotland or Northern Ireland. A Charitable Trust registered in Scotland therefore has the Scottish 9-month filing timetable, while one in England and Wales or Northern Ireland generally has 10 months.
That interaction between structure and jurisdiction is exactly the kind of standard compliance logic a practice management system should be able to deal with.
Once the client is classified properly, the same information can help determine which recurring tasks are appropriate.
A Charitable Company has normal Companies House obligations as well as charity reporting requirements. It will need Accounts and Confirmation Statement tasks alongside Charity Annual Filing.
CIOs and SCIOs do not have the same normal Companies House filing requirements, while Charitable Associations and Charitable Trusts have no Companies House registration.
The combination of work can therefore differ even though the Charity Annual Filing task itself is the same.
The filing deadline should follow the same principle. Once the relevant jurisdiction and year end are known, you don’t want to be calculating and maintaining the deadline manually.
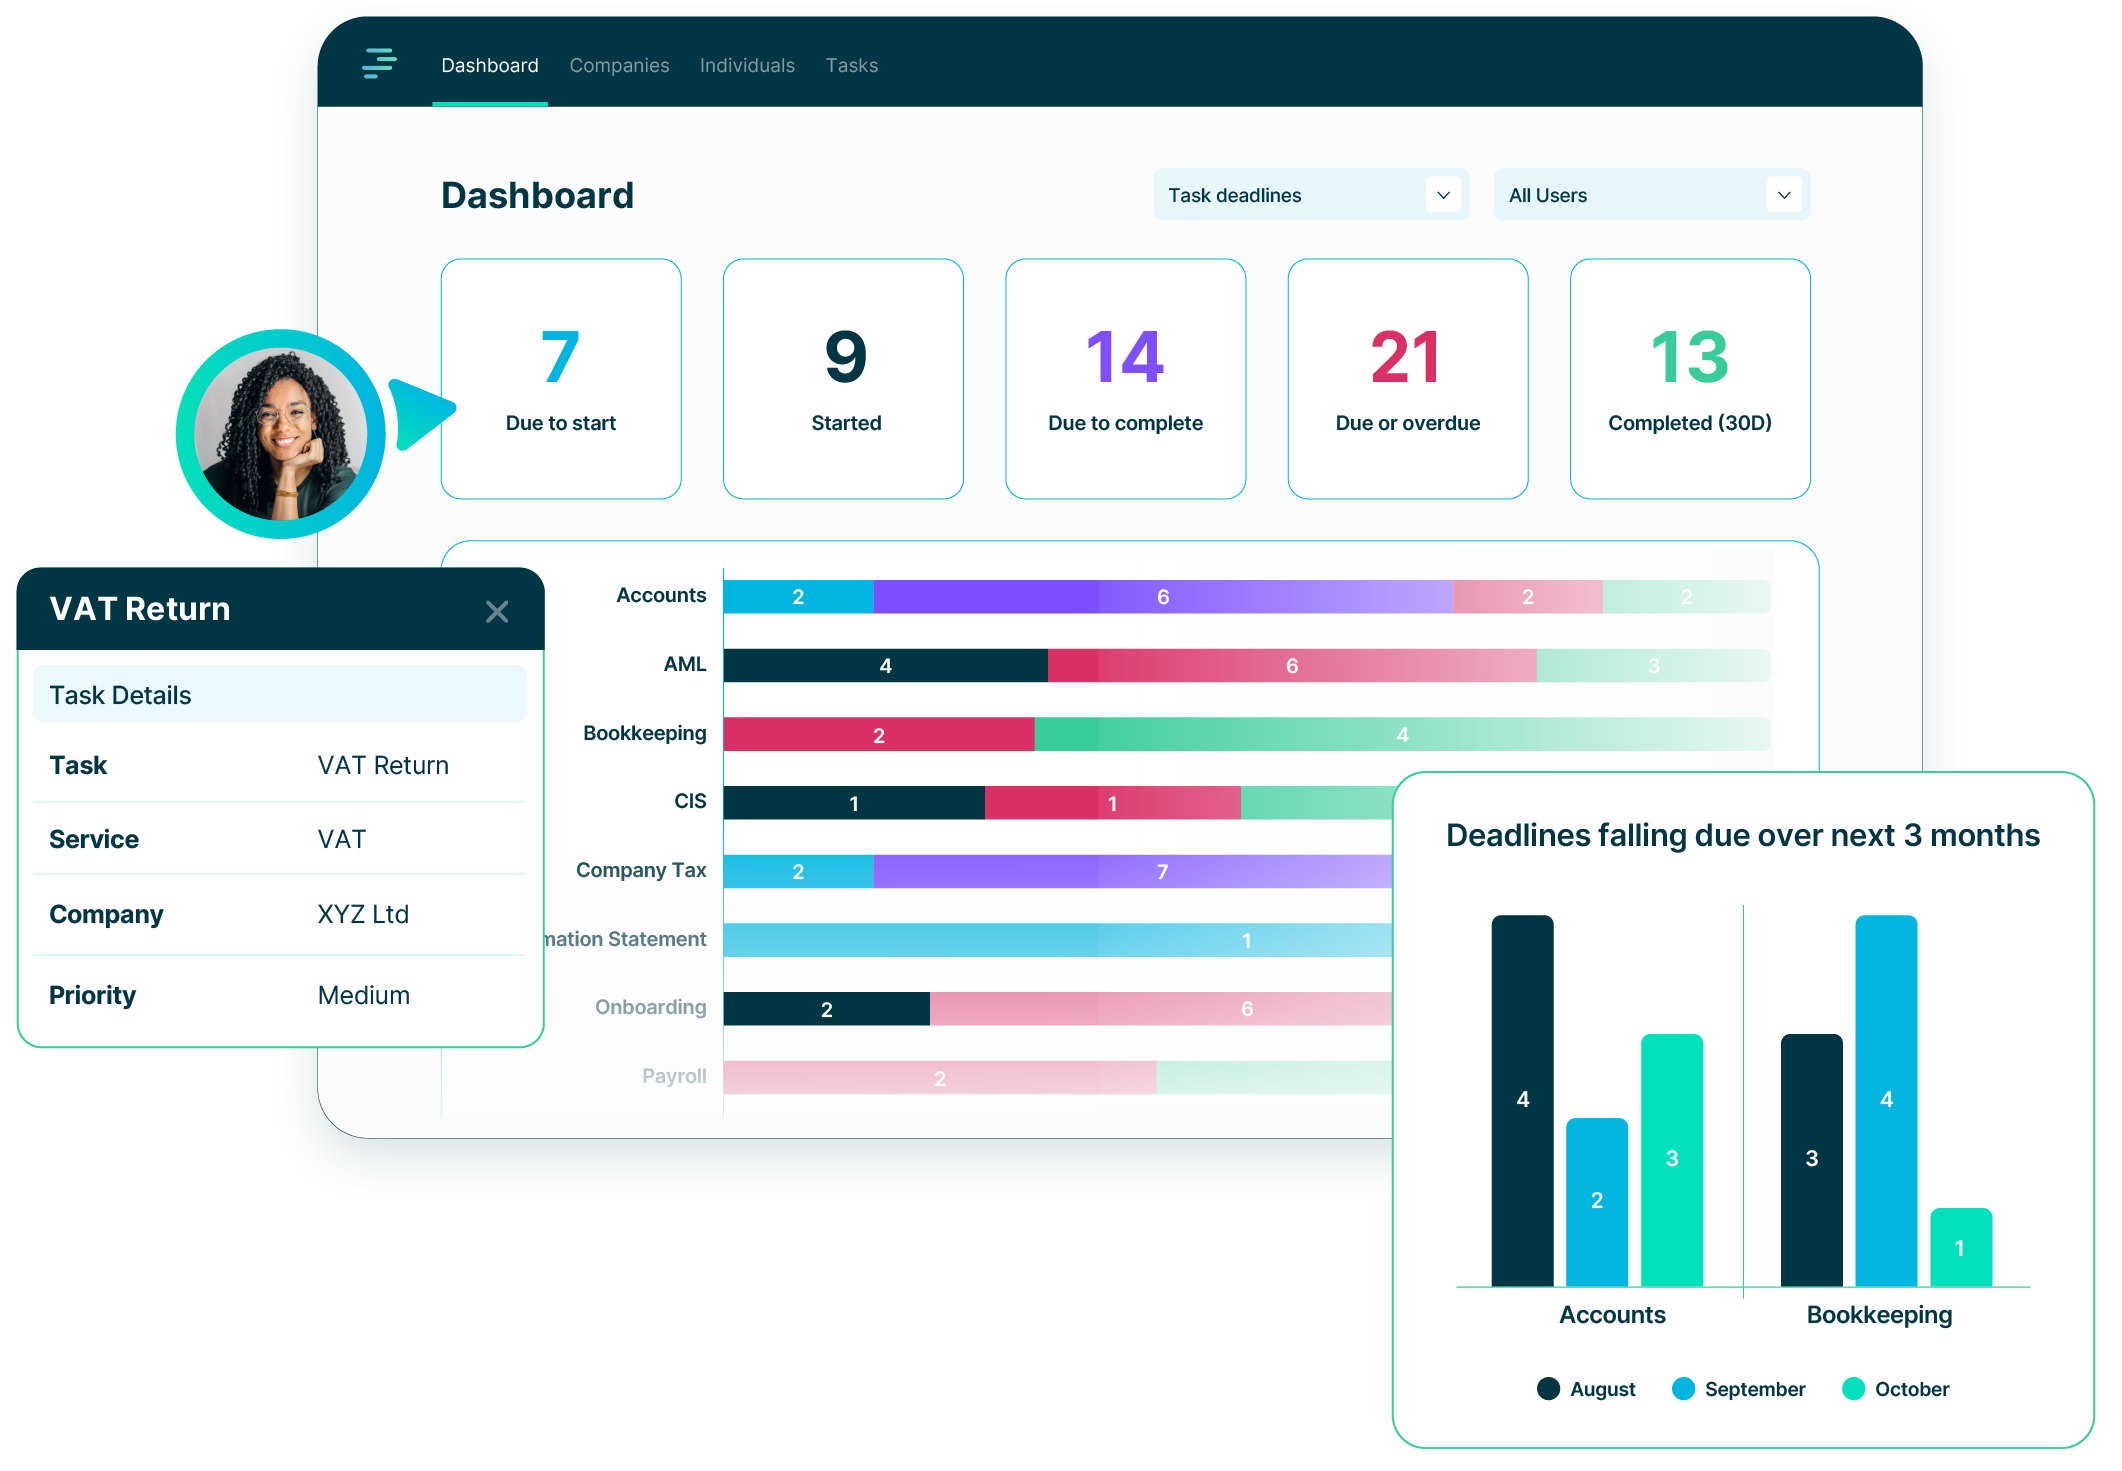
PracticeFlow Smart Tasks are designed to use information already held against the client to determine the standard tasks required and calculate deadlines automatically. For Charity Annual Filing, that means applying the relevant 9 or 10-month timetable from the client information.
A practice management system should deal with the standard compliance logic without requiring you to design a detailed workflow first, while leaving you in control of how the work itself is done.
A charity annual filing process might include preparation of the accounts, the Trustees’ Annual Report, independent examination or audit, trustee approval, the annual or monitoring return and submission to the relevant regulator.
PracticeFlow includes a Charity Annual Filing checklist covering the main stages, but it is a starting point. A firm can amend it or use its own checklist to reflect its procedures and the requirements of individual clients.
The practice management system deals with which standard work applies and when it is due; the checklist defines how your firm carries out that work.
This starts with recording the client properly and avoids having to configure separate workflows simply to make the system understand standard UK compliance obligations, while leaving the firm in control of its own process.
Where Companies House information is available, it can be used rather than entering the same information again. CIOs and SCIOs can be identified through the Companies House search, while Charitable Associations and Charitable Trusts are added using the appropriate organisation type.
The aim is simple: record the client properly once, then use that information throughout the system.
Charities illustrate why accurate client classification matters.
The benefit starts with knowing what clients you have and being able to view and filter them properly. Once that information is structured, it can also help determine the appropriate compliance treatment, tasks and deadlines.
The individual rules may be relatively straightforward. Applying the right rules consistently across a varied client base is where practice management software should help.
For more detail on setting up and working with charities in PracticeFlow, see Working With Charities in the PracticeFlow Help Centre.
Join the growing number of UK accounting and bookkeeping practices using PracticeFlow to stay organised, meet deadlines, and focus on what matters most.